


$ASML: Record quarter and demand for machines all the way to 2030. Why is that alone not enough for a sharp rise in the stock? 👇
ASML is growing, raising margins, and customers want machines years in advance. But when investing, it's not enough to look at records. What matters is what created them, whether they will last, and how much of the future growth is already priced into the stock.
💼 MY POSITION
I have held $ASML since 1 Nov 2024. I bought several times and have already recovered my entire invested amount through subsequent partial sales. The remaining position now represents about 2.32% of my portfolio. Even if its value fell to zero, I would not be at a loss on this investment overall.
📊 Q3 2026 NUMBERS
✅ Revenue €11.66 billion, up 55% year over year.
✅ Net income €4.96 billion, roughly +133%.
✅ Earnings per share €12.95 compared to €5.49 a year ago.
✅ Gross margin 57.5% compared to 51.6% a year ago. It also beat the company's guidance of 55% to 57%.
✅ Operating margin 44.4% compared to 32.8% a year ago.
✅ 121 lithography machines sold compared to 72 a year ago.
System sales brought in about €8.4 billion, of which EUV contributed €4.1 billion including one High-NA machine. Memory accounted for 46% of system sales, logic 54%.
🔎 TWO IMPORTANT CATCHES
According to the analyst consensus used, revenue was roughly in line with expectations or slightly below them. So a record does not automatically mean a surprise for the market.
About €500 million of the profit came from revaluing a stake in Mistral AI. Excluding this item, simple subtraction gives a profit of around €4.46 billion. This is not an official adjusted ASML result, but it shows why the entire reported growth cannot be attributed to machine sales.
💰 STRONG SERVICE AND CASH FLOW
Service and upgrades of existing machines brought in €3.29 billion, almost €400 million more than the company expected. This interest in increasing machine productivity significantly helped the margin.
Free cash flow reached €11.35 billion and cash with short-term investments €12.7 billion. ASML also bought back its own shares for about €4.1 billion. The next interim dividend of €1.88 per share will be payable on 4 November.
However, such cash flow cannot automatically be considered a new quarterly standard.
🏭 WHAT DOES DEMAND SAY?
ASML no longer discloses quarterly orders. However, long-term commitments rose quarter over quarter from €6.2 billion to €12 billion. The CFO confirmed that the increase is mainly related to customer prepayments.
For me, prepayments matter more than optimistic statements. Customers are tying up their own money for future deliveries. They also explain part of the exceptionally strong cash flow: money arrives before the machine is delivered. But they are not in themselves revenue or profit.
Some customers are interested in orders for 2029 and 2030. Interest is not yet a confirmed order. According to management, however, planned capacity for 2027 and 2028 will not cover expected demand.
The company plans a 30% increase in EUV and advanced DUV capacity for 2027. For 2028, it is exploring an increase beyond the additional 30% originally announced.
📈 OUTLOOK AND PRICE INCREASES
For Q4, the company expects revenue of €14.2 billion to €15.2 billion and a gross margin of around 57%. For the full year, revenue of €44 billion to €45 billion and a margin of around 56%.
Agreements on price increases for key products are, according to management, signed. The impact is to begin in 2027 and be fully in effect from 2028.
However, not all of the price increase may end up in profit. Some of the money will go to support suppliers and expand production.
⚠️ WHERE DO I SEE RISKS?
1️⃣ Sustainability of margins. Strong upgrade sales helped the current record, but their future development remains uncertain. In Q4, the margin is expected to be slightly lower despite higher revenue.
2️⃣ Semiconductor cycle. Today's capacity shortage does not guarantee that every new capacity will be fully utilized in a few years.
3️⃣ China and export restrictions. Strong demand is not enough if the company cannot deliver technologies to customers.
4️⃣ Valuation. Even an excellent company can be a poor investment at too high a purchase price.
🧠 WHERE WOULD I START BUYING?
My thesis rests on ASML's unique position in EUV lithography and the need for increasingly demanding technologies in advanced chip production. In my view, this quarter supported it.
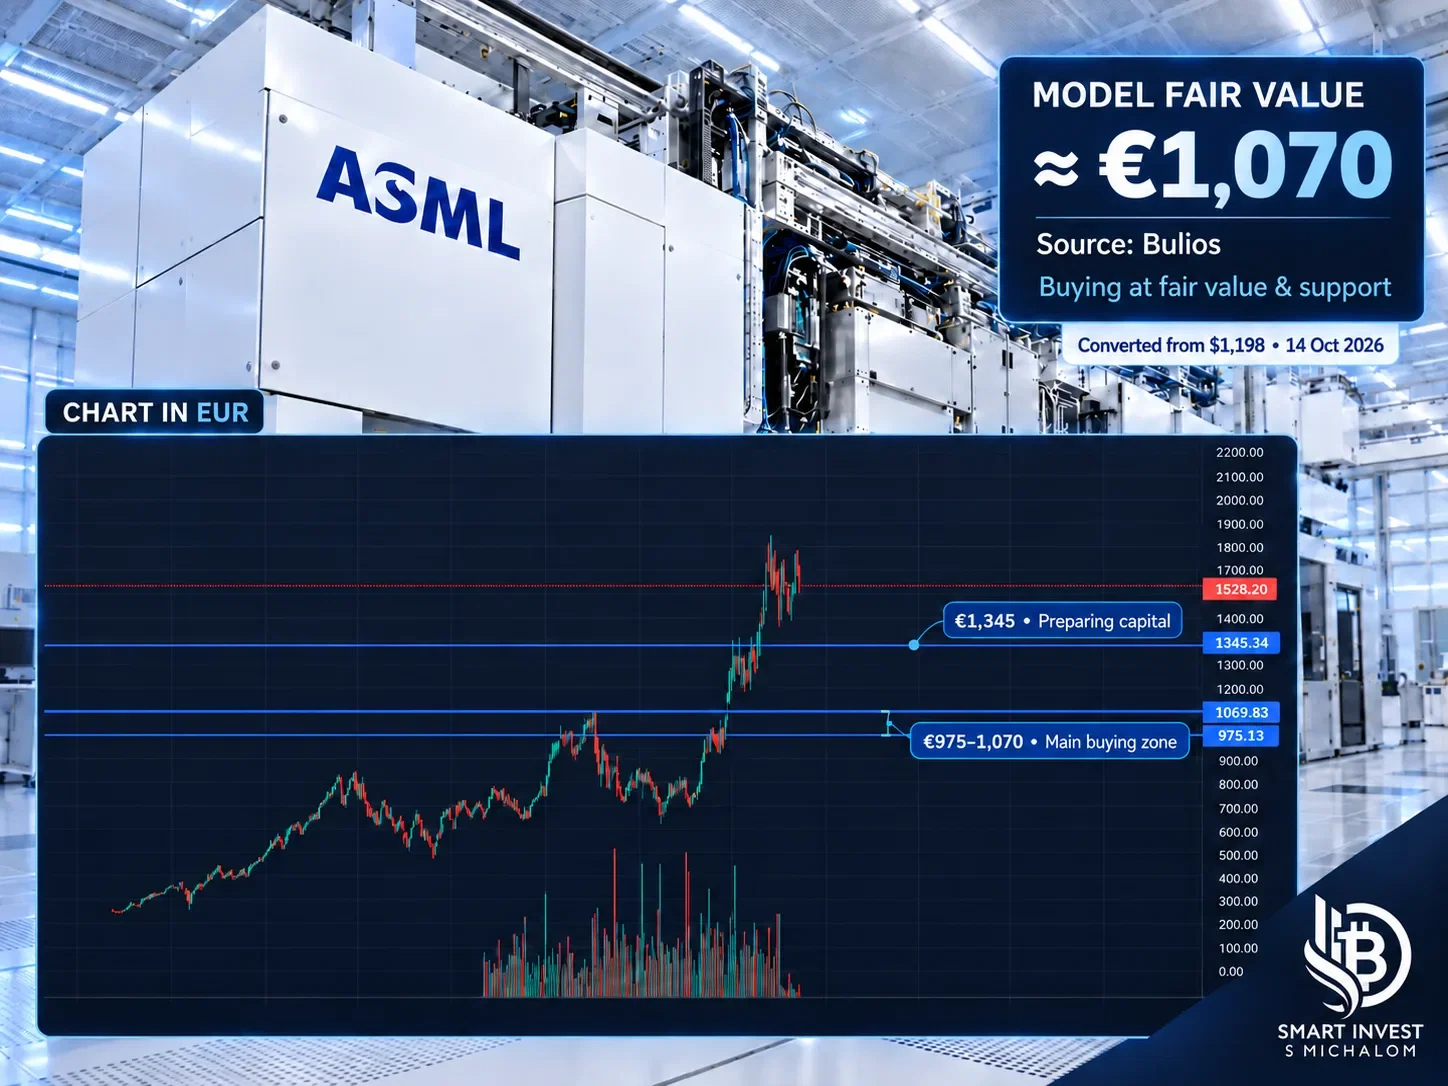
I am holding the position. At a decline to €1,345 I would start watching the price more closely and preparing capital.
The key level for me is around €1,070. Here the model fair value according to Bulios, converted from $1,198, meets significant technical support that I have marked on the chart. At this price I would start adding to the position.
The range of €975 to €1,070 represents my main buying zone. The combination of valuation and technical support is a reason for me to make larger purchases, as long as ASML's results and outlook continue to support my investment thesis.
This is my personal view, not investment advice; the value of an investment can rise and fall, capital loss is possible, and past performance is not a guarantee of future results.
